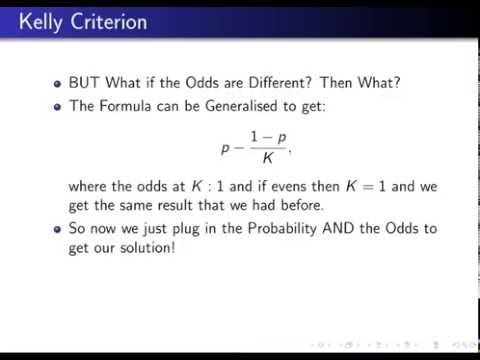
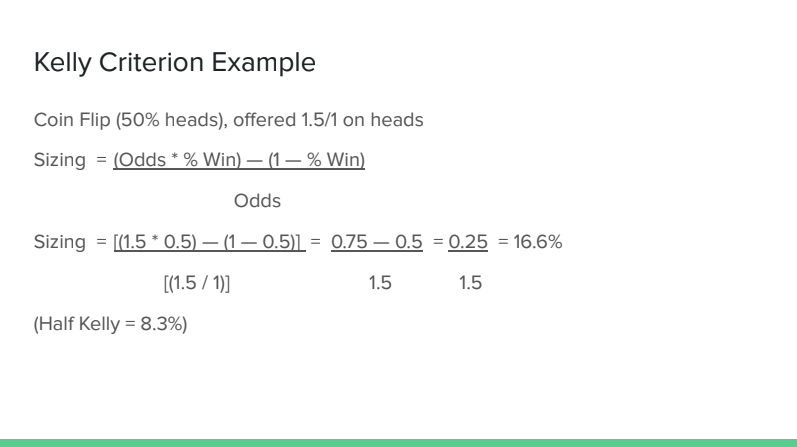
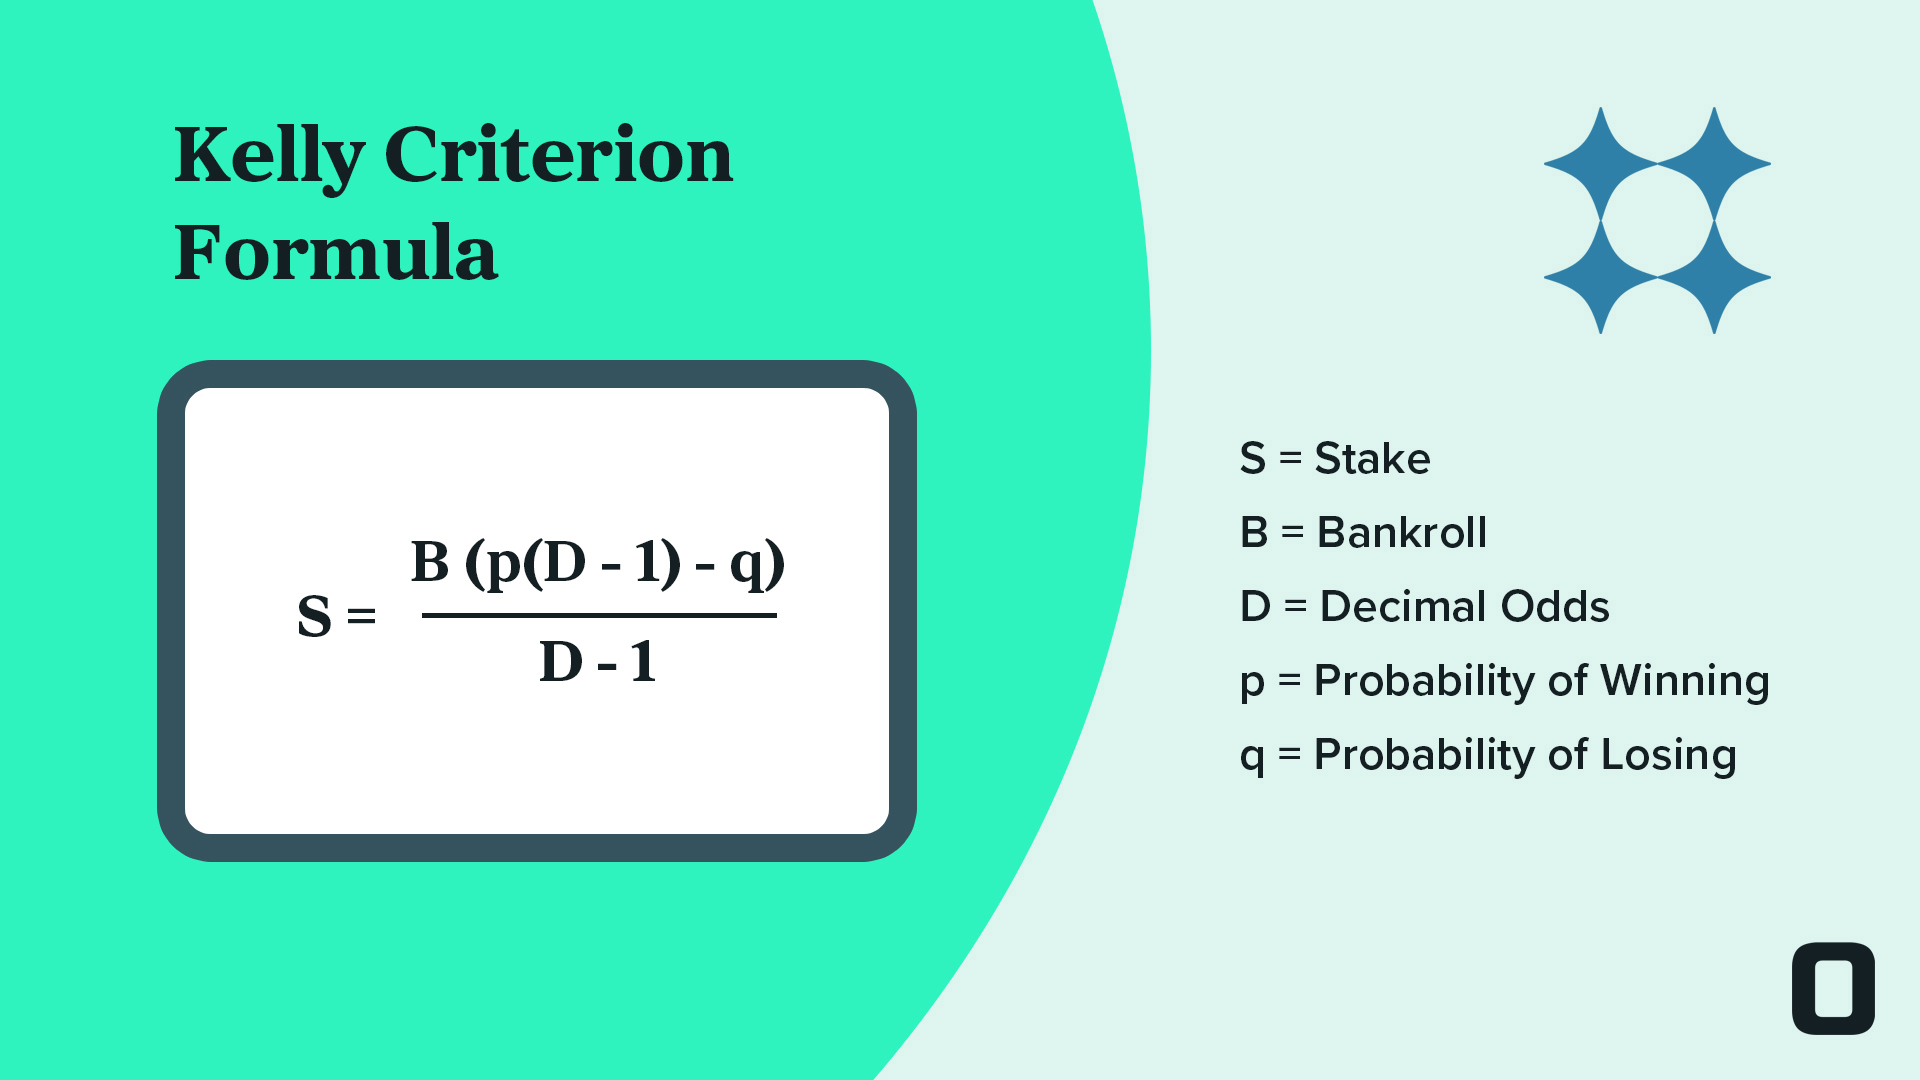
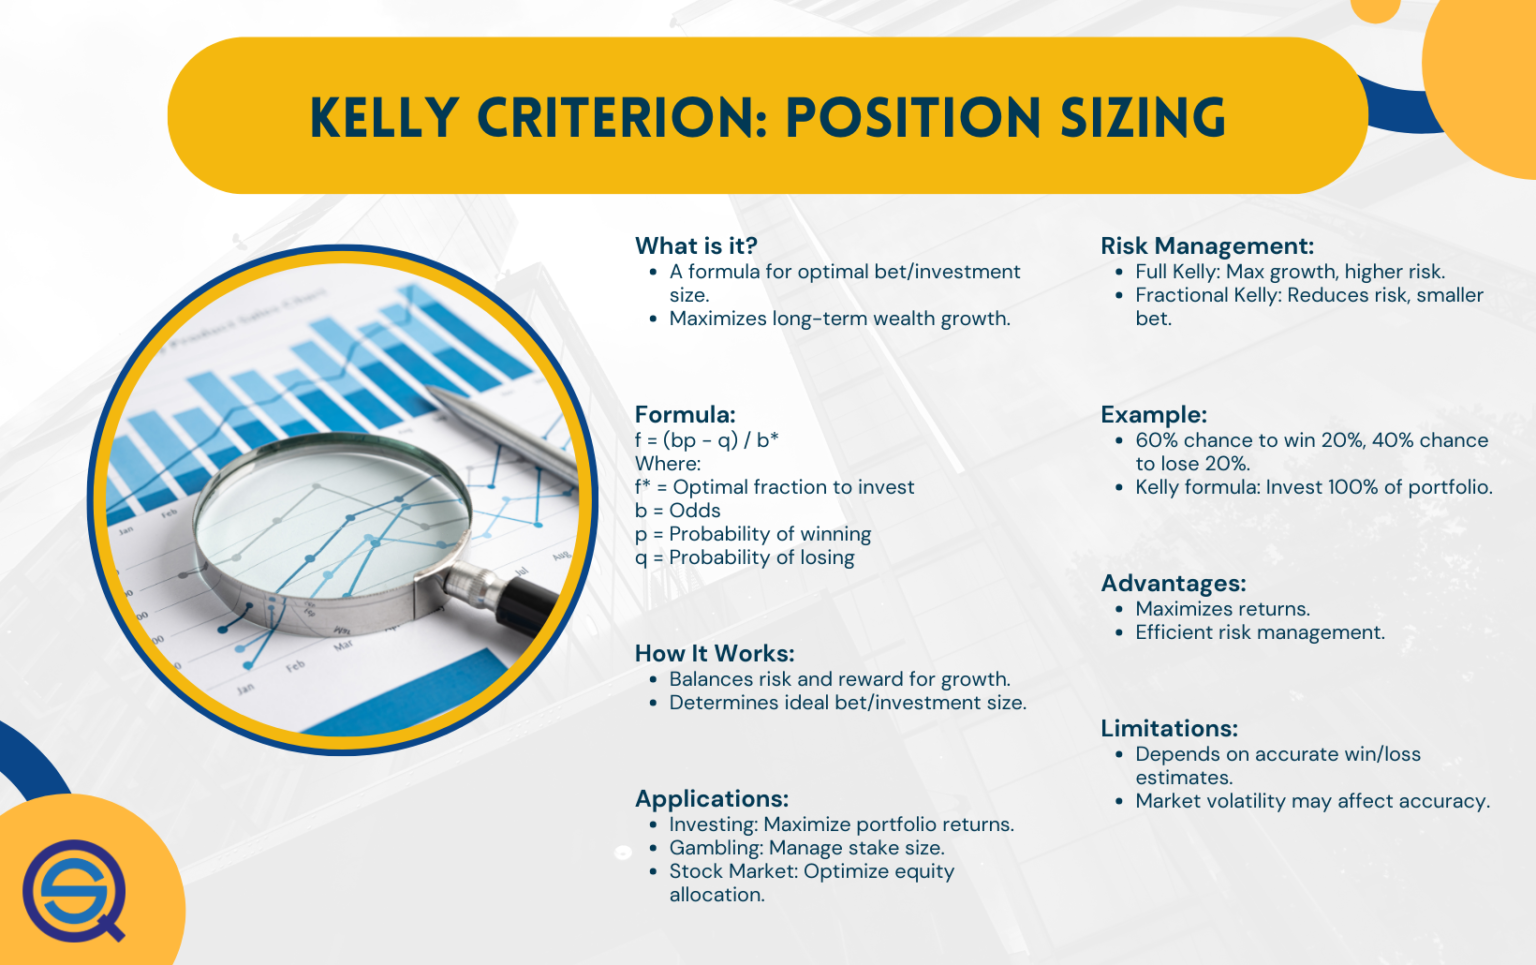
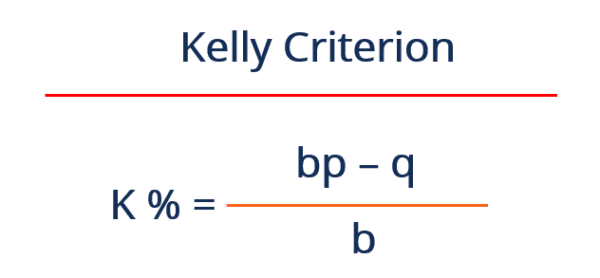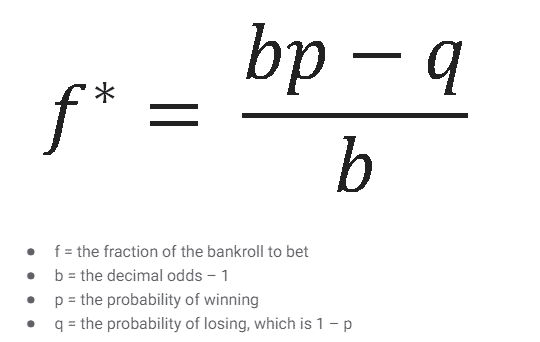In probability theory, the Kelly criterion (or Kelly strategy or Kelly bet) is a formula for risk allocation with the sizing a sequence of bets by maximizing the long-term expected value of the logarithm of wealth, which is equivalent to maximizing the long-term expected geometric growth rate.
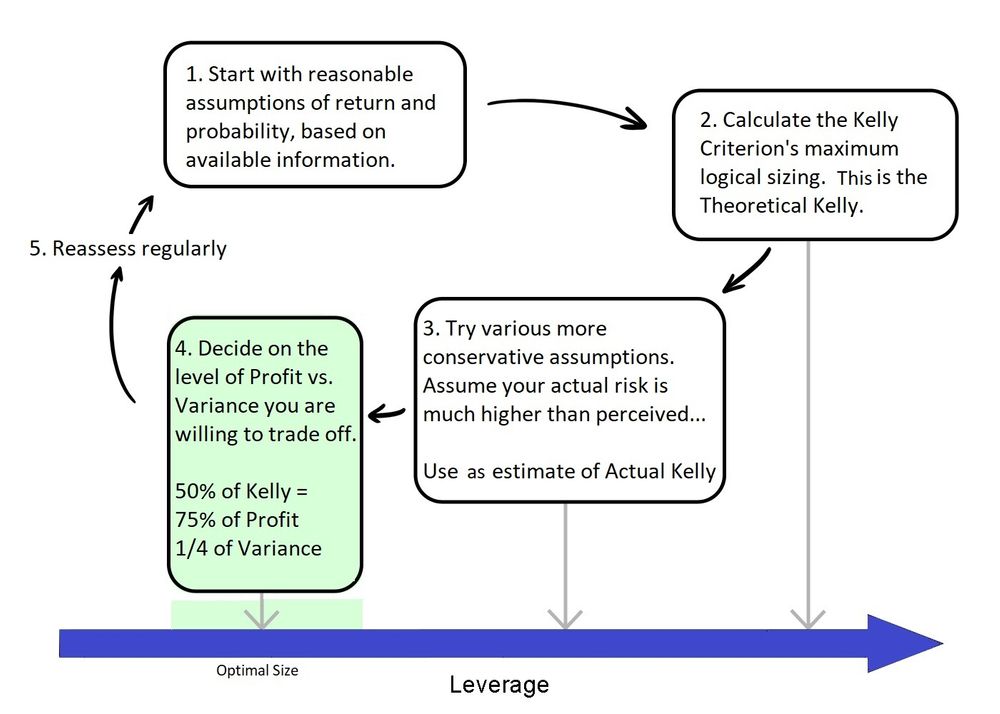
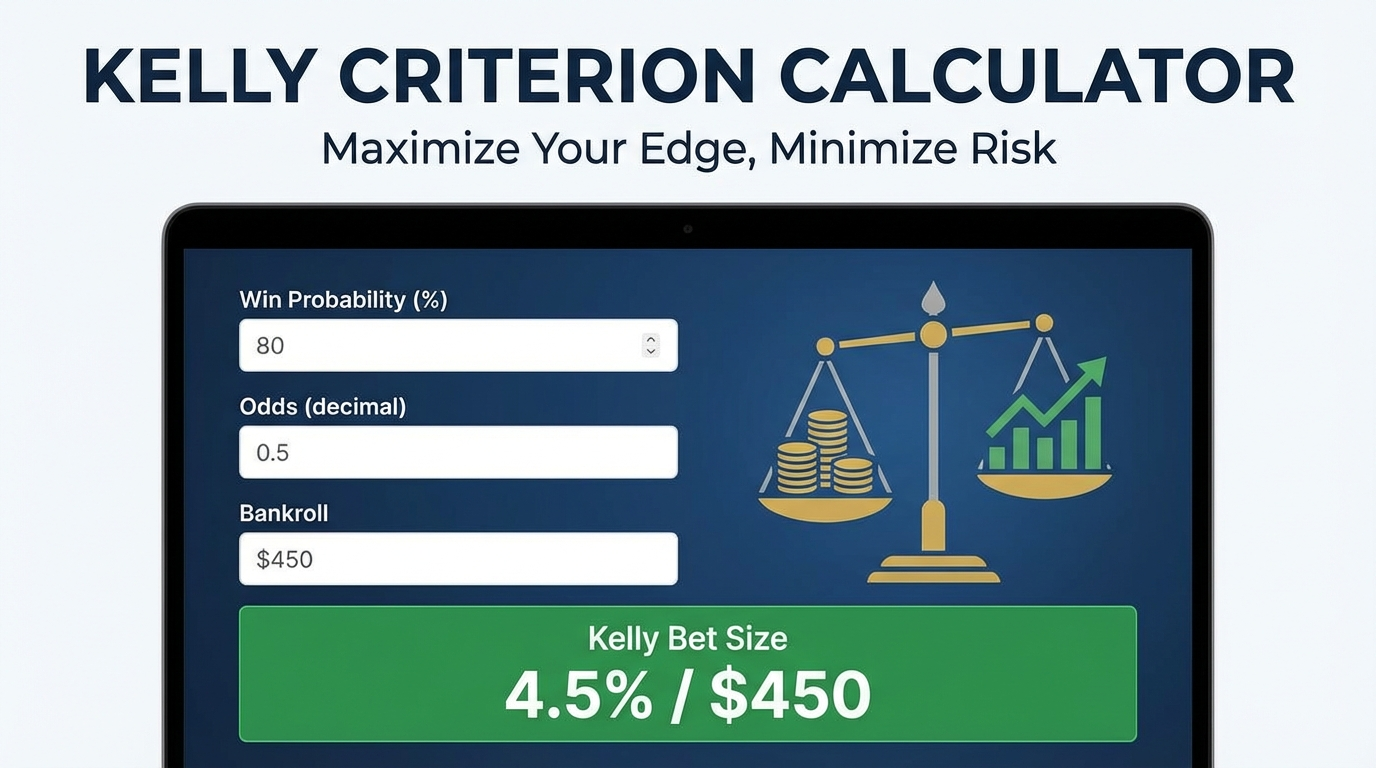
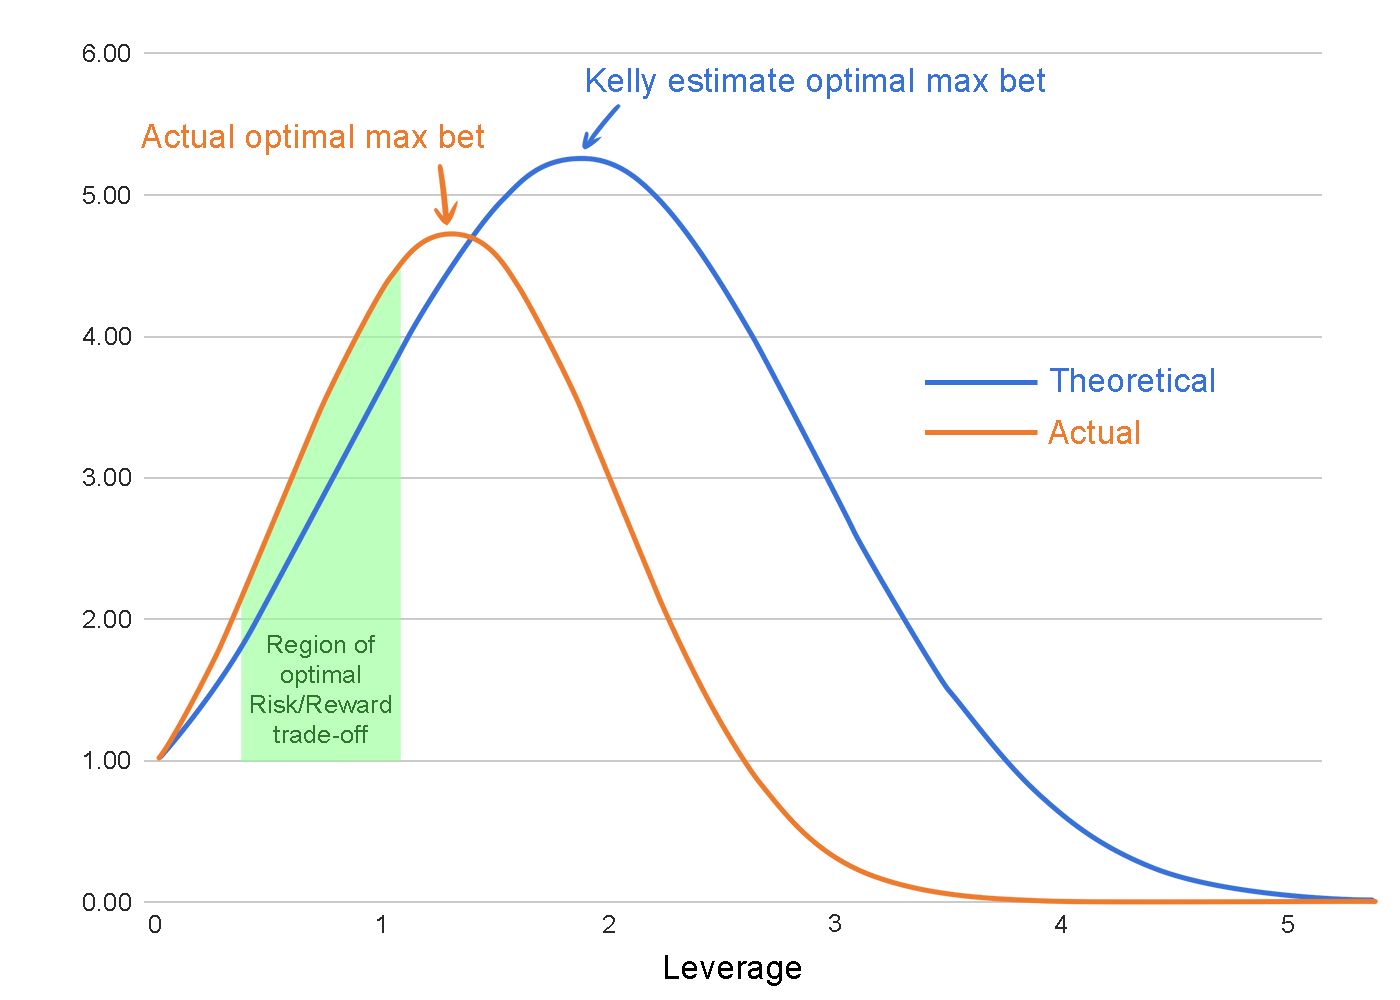
Discover how the Kelly Criterion can enhance your investment strategy. Learn to limit losses, maximize gains, and effectively allocate assets for financial success. Determine the optimal position size for your trades using the Kelly Criterion calculator. Balance risk and reward based on your win rate and risk/reward ratio. lemented a python script to back test the feasibility of Kellys theory. The codes objective was to implement the Kelly criterion on a portfolio of all the components of the S&P500 and compare its performance to both the actual index as well as the SPXEW Monte Carlo calculations are used to directly simulate and compare the average returns from the Mean Variance and Kelly portfolios. The results show that Kelly's Criterion can be used to calculate optimal returns and can generate portfolios that are similar to results from the Mean Variance model. Compares your selected Kelly strategy vs. Fixed 5% betting over time. Shows exact Kelly percentages used and demonstrates the mathematical advantage of optimal bet sizing. Your risk parameters will be explained here. What is full Kelly criterion? Full Kelly maximizes growth but with higher risk of drawdowns. The Kelly Criterion helps traders determine the optimal fraction of their capital to risk on each trade, based on their edge (win rate and risk/reward ratio). Full Kelly is mathematically optimal for maximizing long-term capital growth, but it comes with high volatility. Can Kelly's criterion be used in a portfolio optimization model? A mutation strategy may need to be tailored specifically to the decoupled Kelly problem for different values of risk parameter. In conclusion, the results in this paper show how Kelly's Criterion can be implemented into a portfolio optimization model that combines risk and return into a single objective function using a risk parameter. What is Kelly criterion in probability theory? In probability theory, the Kelly criterion (or Kelly strategy or Kelly bet) is a formula for risk allocation with the sizing a sequence of bets by maximizing the long-term expected value of the logarithm of wealth, which is equivalent to maximizing the long-term expected geometric growth rate. Can Kelly's criterion be used to calculate optimal returns? The results show that Kelly's Criterion can be used to calculate optimal returns and can generate portfolios that are similar to results from the Mean Variance model. The results also show that evolutionary algorithms can be successfully applied to solve this unique portfolio optimization problem. 1. Introduction This research examines the practical implementation of the Kelly Criterion in dynamic markets by developing adaptive strategies that integrate robust parameter estimation and advanced risk management techniques.

This particular example perfectly highlights why From Classic 6040 To Kelly Criterion is so captivating.